Capital for the Battle of Justice: Litigation Funding
There is an old, cynical adage about civil lawsuits in India: “The winner loses, and the loser is destroyed.” According to reports, litigants in India spent an estimated staggering ₹63,000+ crore on lawyer fees and legal expenses last year alone. No matter how strong your truth or merit is, very few possess the financial muscle required to endure protracted courtroom battles.
Take a familiar scenario: Ramesh, a young innovator, sweats for years to build ground-breaking software. Soon, a multinational tech giant steals his intellectual property and amasses crores in profits. Ramesh has indisputable evidence and the truth on his side. However, his opponent commands an army of top-tier advocates and deep financial reserves. If the dispute stretches over a decade, Ramesh’s resources will dry up, driving his fledgling startup into liquidation before a verdict is ever reached.
To level the playing field for the underdog in such mismatched battles, a transformative concept is gaining traction in Indian legal circles: Third-Party Litigation Funding (TPLF).
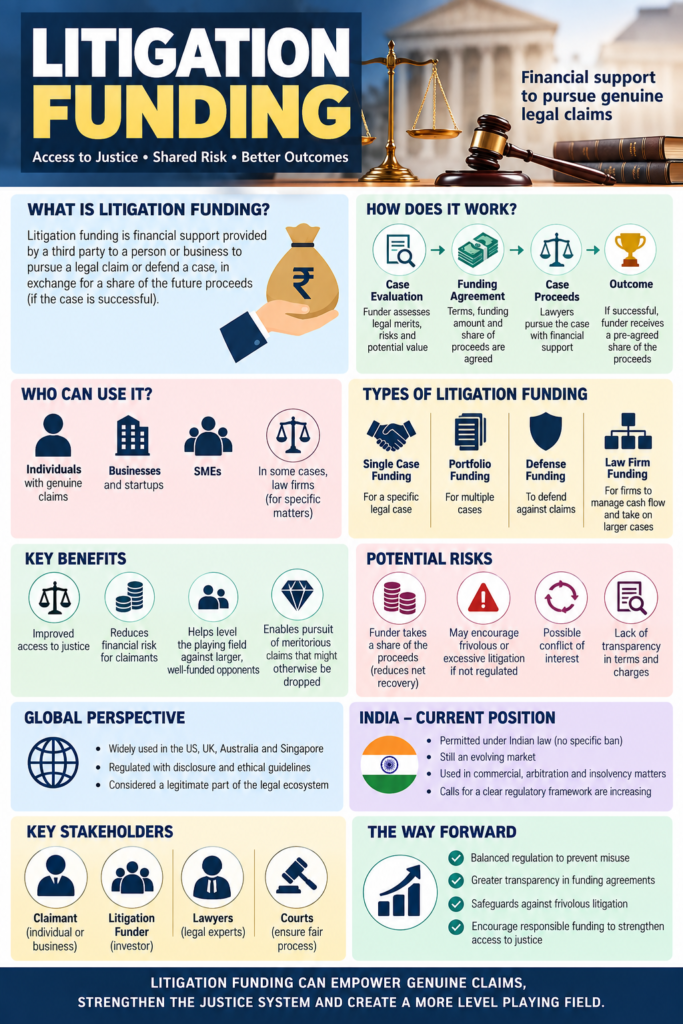
What Exactly Is Litigation Funding?
In simple terms, an unrelated third party—such as an investment bank, institutional hedge fund, or dedicated litigation financier—finances the plaintiff’s legal journey by covering advocate fees, court duties, and expert witness expenses.
- The Winning Scenario: If the plaintiff wins and secures a financial recovery, the funder earns a pre-agreed percentage of the proceeds.
- The Losing Scenario (Non-Recourse): If the case fails, the litigant pays back nothing. The funder absorbs 100% of the financial loss.
This mechanism delivers immense strength to ordinary individuals and emerging enterprises who might otherwise be priced out of justice.
At first glance, this might raise eyebrows: Why would a stranger invest in someone else’s courtroom clash? The answer is strictly financial—it is an alternative asset class. Just as venture capitalists back companies based on future market growth, a litigation funder evaluates the legal merits of a claim and invests in its anticipated judgment or settlement. If the claim succeeds, they gain returns; if it collapses, they shoulder the risk.
While third-party financing is not entirely alien to India, it is now maturing into an institutionalized sector, seeing widespread application across high-stakes commercial disputes, international arbitrations, and corporate insolvency resolutions.
The Legal Landscape in India for Litigation Funding :-
Indian law does not broadly prohibit third-party litigation funding.
- Supreme Court Recognition: In the landmark 2018 ruling (Bar Council of India v. A.K. Balaji), the Supreme Court clarified that there is no general legal bar preventing independent third parties from funding lawsuits, provided they are not practicing advocates representing the party.
- State Civil Codes: States including Maharashtra, Gujarat, Karnataka, and Madhya Pradesh have acknowledged third-party financiers through amendments to their Civil Procedure Codes.
- Global Precedents: Jurisdictions like Singapore and Hong Kong have proactively created formal statutory frameworks recognizing third-party funding in international arbitration.
- Key Ethical Guardrails: While external non-parties can invest, practicing advocates in India remain barred by professional codes from funding their own clients’ matters or charging contingency fees tied to outcomes.
Because India still lacks a dedicated, standalone statute regulating the sector, arrangements are governed by general contract law, judicial precedents, and legal professional ethics.
Ethical Dilemmas and Structural Challenges :-
Despite its democratizing potential, third-party financing presents complex friction points:
- Loss of Case Autonomy: When a commercial funder’s money is on the line, who truly calls the shots—the original plaintiff seeking accountability, or the investor maximizing an internal rate of return?
- Confidentiality & Privilege: Sharing non-public evidentiary material and strategy with outside financiers risks compromising attorney-client privilege.
- Predatory Economics: Unregulated financiers could exploit vulnerable, financially desperate claimants by enforcing lopsided agreements that take an excessive share of the recovery.
Striking the Right Balance :-
When external capital steps in to protect its downside, investors may attempt to influence litigation tactics, settlements, or withdrawal terms. In the 2023 ruling (Tomorrow Sales Agency v. SBS Holdings), the Delhi High Court delivered a significant finding: a third-party funder who is not a formal party to the proceedings cannot be held liable for adverse cost awards merely by virtue of funding the dispute. Crucially, the court emphasized the urgent need for structural transparency and safeguards against exploitative terms.
Litigation funding cannot simply be celebrated as “benevolent charity for justice,” nor should it be dismissed as mere “financial speculation on court disputes.” It sits at the intersection of access to justice and capital market dynamics.
Legal battles must never remain the exclusive privilege of deep corporate pockets, and a righteous claim should never perish simply due to a lack of funds. To prevent this vehicle from morphing into unbridled courtroom gambling, establishing clear, balanced regulatory guardrails is an urgent necessity. A system where money funds justice—rather than one where justice belongs only to those with money—is an essential pillar of an equitable democracy.